
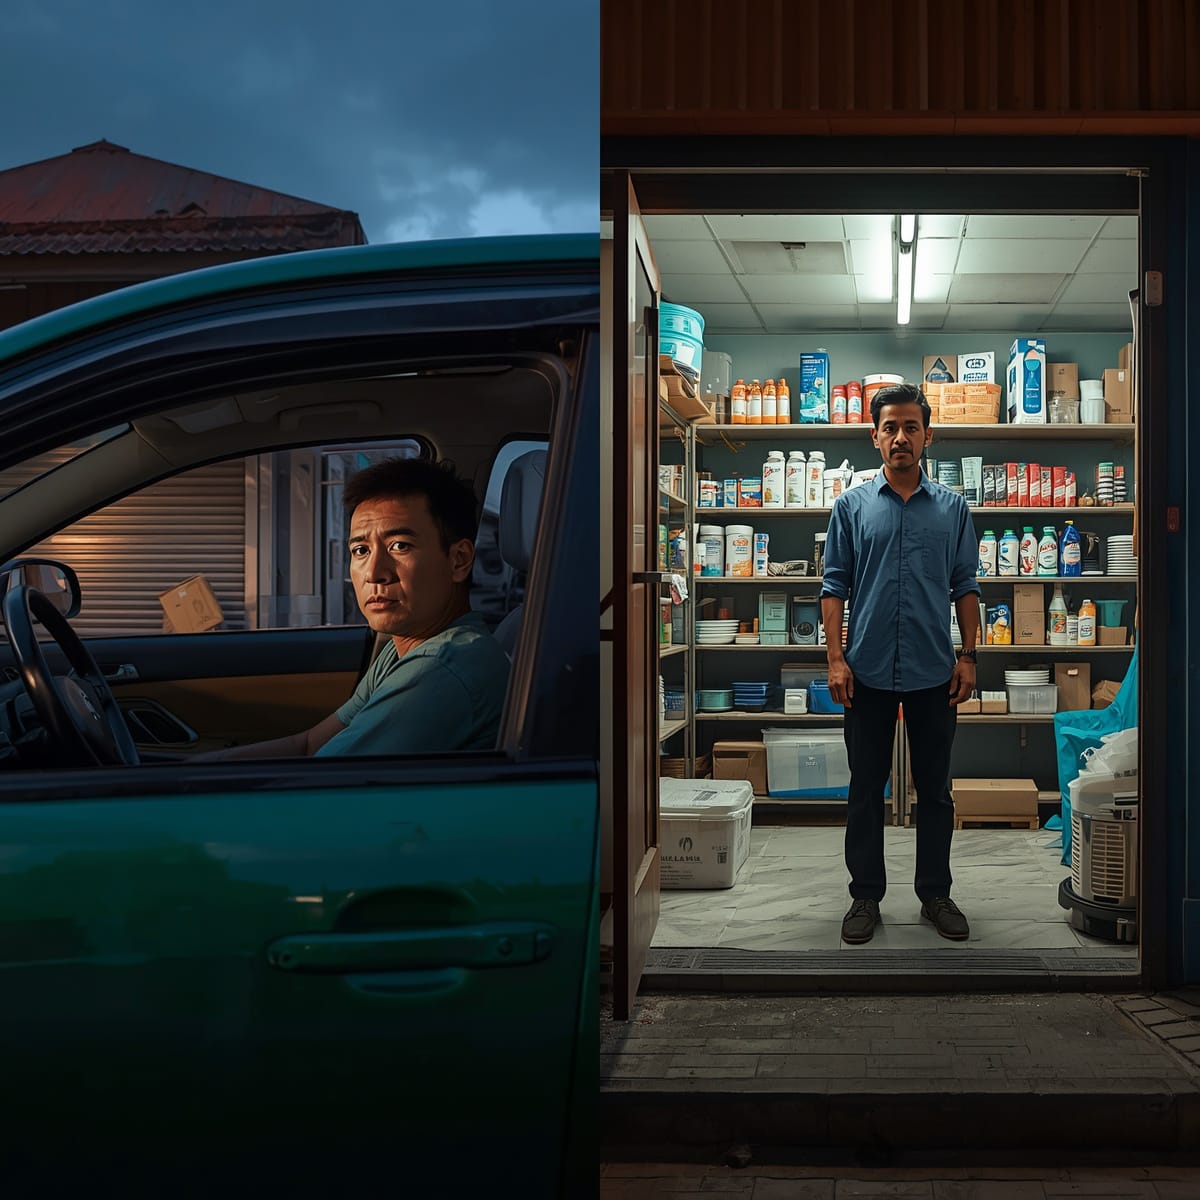
How two Malaysian brothers started with the same capital but ended up with very different business journeys.
In January 2021, two brothers, Ahmad and Azman, stood outside two newly rented shoplots in Bandar Teknologi Kajang.
Two Brothers. Two Shops. One Important Lesson.
Their father, Pak Rahman, had spent almost 25 years running a small household goods wholesale business. He wanted his sons to become independent, so he gave each of them RM50,000 to start their own businesses.
Both brothers decided to open household goods shops.
Both rented similar shoplots, bought stock from some of the same suppliers, and served customers from the same neighbourhood.
Their shops were only two streets apart.
Same father. Same experience. Same starting capital.
Five years later, however, their stories would be very different.
Year 1: Business was good. Or so they thought.
By December 2021, both shops appeared to be doing well.
Ahmad’s shop, Rahman Household Supplies, was busy most weekends. Customers came in for kitchenware, cleaning products, plastic containers and everyday household items.
Azman’s shop, Azman Home & Trading, was doing roughly the same business.
Both brothers were happy.
When their father asked how business was going, Ahmad replied:
“Alhamdulillah, Ayah. Banyak jual. Duit pun ada.”
But there was a difference in how they managed their businesses.
Ahmad: Money came in, money went out.
Ahmad used his personal bank account for everything.
Customer payments, supplier payments, family expenses, car instalments and children’s school fees all came from the same account.
Some sales were recorded in a notebook. Others were simply forgotten.
When suppliers asked for payment, he checked his bank balance and paid whoever was most urgent.
He never prepared a monthly profit and loss statement.
His business measurement was simple:
“If there is money in the bank, business must be okay.”
Azman: Know your numbers before making decisions.
Azman took a different approach.
He opened a separate bank account for the business and another for personal expenses.
He recorded sales and purchases, kept supplier invoices, monitored stock and reviewed his expenses every month.
At the end of each month, he wanted answers to three questions:
- How much did the business sell?
- How much did it actually earn after costs and expenses?
- How much cash was available to operate the business?
He also reviewed which products sold quickly, which products had better margins, and which items were taking up shelf space without generating enough returns.
Ahmad laughed at him one evening.
“Man, kau buka kedai atau buka pejabat akaun? Every month busy with figures!”
Azman smiled.
“Kalau aku tak tahu nombor aku, macam mana aku nak tahu kedai aku untung atau rugi?”
Year 2: The money started disappearing.
By 2022, Ahmad’s shop still looked busy.
But behind the counter, things were becoming uncomfortable.
His suppliers started calling about overdue payments.
He checked his bank account and wondered where all the money had gone.
The previous month, he had used business collections to repair his family car, pay school expenses and take his family on a short holiday.
He had not realised how much money he had withdrawn from the business.
He was selling products, but he was also spending money that was needed to replace stock and pay suppliers.
The problem was not necessarily a lack of sales.
It was the lack of financial visibility.
Azman’s business also experienced slow periods.
However, his accounting records helped him identify the pressure points.
He knew how much money customers owed him, how much he owed suppliers, how much stock he held, and which expenses needed attention.
He also began negotiating better purchasing arrangements with selected suppliers.
Instead of simply trying to sell more, he started asking a different question:
“How can I improve the profitability of this business?”
That question changed the way he operated.
Year 3: The market became tougher.
In 2023, both businesses faced higher operating costs.
Supplier prices increased. Rental costs went up. Customers became more careful with their spending.
Ahmad reacted by cutting prices.
He wanted to attract more customers, so he offered discounts on almost everything.
Unfortunately, he did not calculate whether those discounts still left enough gross profit to cover his operating expenses.
Some products were being sold at very low margins. Others were barely profitable after delivery and handling costs.
His sales figures looked reasonable, but his cash position became increasingly tight.
He started blaming the economy.
“Business sekarang memang susah. Semua benda naik harga!”
Azman also felt the pressure.
But because he had records, he could investigate what was happening.
He reviewed his product margins and noticed that some fast-selling products were not necessarily his most profitable products.
He adjusted his product mix, reduced unnecessary stock purchases and focused on items that offered better returns.
He also started talking to customers.
He discovered that several small restaurants and food businesses in the area regularly needed bulk quantities of certain household and cleaning products.
Instead of waiting for walk-in customers, he began offering scheduled deliveries and bulk purchasing arrangements.
This was business development.
He was no longer just waiting for customers to enter his shop.
He was finding new opportunities within the market.
Year 4: One shop was struggling. The other was evolving.
By 2024, Ahmad was exhausted.
He spent most of his time trying to solve immediate problems.
A supplier wanted payment. A customer complained. Stock was missing. The bank balance was low.
He was constantly working, but he could not confidently explain whether his business was making money.
Azman, meanwhile, had started using his financial information to plan ahead.
He reviewed customer purchasing patterns, negotiated with suppliers, and introduced simple delivery arrangements for regular business customers.
He did not expand recklessly.
Before taking on additional costs, he considered whether the expected sales and gross profit could support them.
His accounting records were not just for tax or compliance.
They had become tools for making business decisions.
That was the difference between recording what happened and using the information to decide what should happen next.
Year 5: Two very different endings.
In January 2026, Ahmad finally made the difficult decision to close his shop.
After five years of hard work, he could no longer sustain the business.
The remaining stock was sold off, the shoplot was vacated, and the shutters came down.
Today, Ahmad drives Grab around Kajang and Bangi.
He works hard, picks up passengers, and earns an honest living while rebuilding his finances.
He has no reason to be ashamed. Life sometimes takes us in unexpected directions.
But one evening, when he met Azman for dinner, he admitted something.
“Man, kalau aku dulu jaga akaun betul-betul, mungkin aku boleh nampak masalah tu lebih awal.”
Azman did not lecture him.
He simply replied:
“Bang, kita sama-sama belajar. Aku pun buat silap. Bezanya, aku cuba tengok nombor sebelum buat keputusan.”
Azman’s shop had also changed.
He had developed regular business customers, improved his purchasing arrangements and built a more organised operation.
In March 2026, he opened a second outlet.
It was not because he had a secret formula or extraordinary luck.
He had learned to understand his business, use financial information, and identify opportunities before committing resources.
So, what was the real difference?
Let’s be clear.
Accounting alone does not guarantee business success. Having a separate bank account does not automatically make a business profitable. And a good business system cannot eliminate every market risk.
Both brothers faced the same economic environment, but their decisions were supported by different levels of information.
The important difference was that Azman used accounting as a management tool, not merely as a record of past transactions.
Here are five lessons every SME owner can take from their story.
1. Separate business and personal finances.
Keep business collections and expenses separate from personal spending.
Pay yourself through a planned owner’s salary or drawings arrangement, properly recorded according to your business structure.
This makes it easier to understand the actual financial position of the business.
2. Record every transaction.
Sales, purchases, expenses, supplier payments and customer receipts should be recorded accurately.
Keep supporting documents such as invoices, receipts and payment records.
If your records are incomplete, your financial reports may not tell the full story.
3. Understand profit, not just sales.
A business can have RM100,000 in monthly sales and still struggle financially.
For example:
| Description | Amount |
|---|---|
| Monthly sales | RM100,000 |
| Cost of goods sold | RM65,000 |
| Gross profit | RM35,000 |
| Operating expenses | RM25,000 |
| Profit before tax and other applicable adjustments | RM10,000 |
The business did not earn RM100,000.
Its illustrative operating result was RM10,000 before tax and any other applicable adjustments.
Understanding this difference helps owners make better decisions about pricing, purchasing, expenses and growth.
4. Use accounting information to develop your business.
This is where accounting and business development come together.
Your financial records can help answer questions such as:
- Which products generate the best gross profit?
- Which customers contribute the most to revenue?
- Are discounts improving sales but damaging margins?
- Can the business afford another employee or outlet?
- Is expanding into wholesale or delivery services commercially viable?
- How much working capital is needed to support growth?
These are not merely accounting questions.
They are business development decisions supported by financial information.
5. Plan before expanding.
Growth is not simply about opening another branch or increasing sales.
Before expanding, understand the additional costs, expected revenue, cash flow requirements, staffing needs and operational risks.
A business should grow because the numbers and market opportunity support it — not simply because the owner feels ready.
Are you Ahmad or Azman?
Perhaps you recognise a little of yourself in both brothers.
You work hard. You serve your customers. You deal with suppliers, staff, family responsibilities and rising costs.
But when was the last time you sat down and properly reviewed your business figures?
Do you know your actual profit last month?
Do you know which products or services are making you money?
Can you tell whether your business has enough cash to meet its next three months of commitments?
And most importantly, are you using your financial information to make better business decisions?
You do not need to wait until business is struggling before you start.
Accounting tells you what is happening in your business. Business development helps you decide what to do next.
At HacheBC, we believe that no two businesses are the same.
Our approach begins with understanding your business, reviewing its financial information and identifying practical areas for improvement.
Whether you need help with accounting, financial clarity, tax-related support or business development, the starting point is always understanding where your business stands today.
If you are ready to understand your numbers and explore how to improve your business, let’s have a conversation.
HacheBC — Minding Your Business Matters.